← GridteamAI

Purchase access

This is part of the paid GridteamAI Quarterly Sector Report.

Purchase access — book@gridteamai.com

£295 single volume · £995/yr annual · Team £2,495 · Enterprise £4,995 · Corporate £9,995. Secure checkout coming soon; email to purchase today.

GridteamAI · Quarterly Sector Report · Gap 37
UK Strategic Resource Options — the reservoirs, transfers and recycling being built under WRMP24 · RAPID-gated · Water beachhead
Series consistency · canonical Gap-series system
A4 · 210 × 297 mm · 3 mm bleed (not shown)
UK English · ~30 pp · v2.1 / Q1 2030
FRONT MATTERi · Cover · ink · full bleed
GridteamAI
Quarterly Sector Report
Volume Gap 37
Water Utilities · Strategic Resource Options
by GridteamAI
UK · Reservoirs · Transfers · Recycling · RAPID England & Wales · Q1 2030

What’s
Being Built.

Reservoirs, transfers and recycling, RAPID-gated — the £20–30 bn programme that reopens UK water construction after thirty years.

gridteamai.com · book@gridteamai.com v2.1 · Q1 2030 Water · Volume 3
05 — 06Executive summary · spread
UK Strategic Resource Options · Executive summary05
00 · Executive Summary A two-page brief

Reservoirs, transfers and recycling — the largest water build in three decades.

The SRO portfolio is the most significant UK water infrastructure construction programme since the 1990s — a £20–30 bn portfolio of reservoirs, inter-regional transfers, water recycling and desalination delivered across 2025–2040.

The lead reservoirs are Anglian’s Lincolnshire and Fens, Thames’s SESRO (Abingdon) and Southern’s Havant Thicket — the latter already under construction, the first major UK reservoir since Carsington (1992). The lead transfers are the Severn-Thames and Grand Union Canal; the lead recycling schemes are Teddington and Beckton Reuse.

RAPID coordinates the gated approval — strategic review, development, design, construction, operations — with cross-regulator alignment at each gate and a PR24/PR29/PR34 funding tranche behind each. Most SROs are NSIPs requiring Development Consent Orders; cost escalation through the gates is the principal financial risk.

The Q1 2030 picture

GridteamAI base case: Havant Thicket operational; the Anglian reservoirs and SESRO progressing through RAPID Gates 2–3 with NSIP consent in train; Severn-Thames and Grand Union in development; Thames Water restructuring the principal execution risk for SESRO and Teddington.

The shape of this volume. Section 1 sets out the headline figures. Section 2 develops twelve findings, each confidence-annotated. A chapter-weight pull at p. 14 anchors the argument. Section 3 steps through the reservoirs, transfers and recycling portfolio. Section 4 covers RAPID gates and consenting. Section 5 covers supply chain, risks and the outlook. Section 6 makes recommendations, with a one-page tear-out at p. 25.

Executive summary · ends1 · The headline figures · p. 07
09 · FIG. 11 · SRO portfolio overview · restyled -v2
1 · The headline figures09
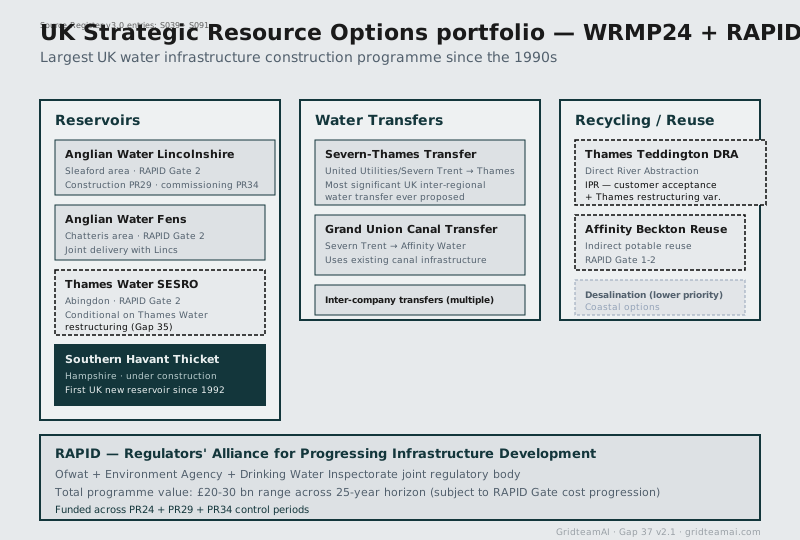
Figure 1 · The SRO portfolioWRMP24 · RAPID

Reservoirs, transfers and recycling — a £20–30 bn portfolio.

The SRO portfolio across three categories: reservoirs (Anglian Lincolnshire + Fens, Thames SESRO, Southern Havant Thicket under construction), transfers (Severn-Thames, Grand Union Canal) and recycling/reuse (Teddington, Beckton). RAPID-coordinated, gated, and funded across PR24/PR29/PR34.

The UK Strategic Resource Options portfolio in three columns. Reservoirs: Anglian Water Lincolnshire (Sleaford, RAPID Gate 2, construction PR29, commissioning PR34) and Fens (Chatteris, Gate 2, joint delivery); Thames Water SESRO (Abingdon, Gate 2, shown ink-dashed as conditional on Thames Water restructuring, Gap 35); and Southern Havant Thicket (Hampshire, under construction, shown in solid teal as the first UK new reservoir since 1992). Water Transfers: the Severn-Thames Transfer (United Utilities and Severn Trent to Thames, the most significant UK inter-regional water transfer ever proposed), the Grand Union Canal Transfer (Severn Trent to Affinity Water, using existing canal infrastructure), and multiple inter-company transfers. Recycling and Reuse: Thames Teddington Direct River Abstraction and Affinity Beckton Reuse (both ink-dashed as IPR with customer-acceptance and Thames restructuring variables), and desalination at lower priority. A footer notes RAPID — the Ofwat, Environment Agency and Drinking Water Inspectorate joint body — coordinates a £20-30 bn programme across the 25-year horizon, funded across PR24, PR29 and PR34.
Fig. 1 / Section 1

Havant Thicket (teal) is building; SESRO and the IPR schemes (ink-dashed) carry conditionality. RAPID-gated, £20–30 bn.

Quarterly Sector Report · Gap 372 · Twelve findings · p. 10
09 — 102 · Twelve findings · 01 – 03
2 · Twelve findings on the SRO portfolio10
2 · Twelve findings on the SRO portfolioQ1 2030

Twelve findings. Each carries a confidence level.

HIGH — verified against RAPID, Ofwat, a WRMP24 plan, the Planning Inspectorate NSIP register or a named undertaker. MEDIUM — named UK industry coverage cross-referenced to a primary source. LOW — GridteamAI scenario projection, marked as such.

Findings 01 – 12 · summary

  1. 01The SRO portfolio is the largest UK water build since the 1990s.
  2. 02Anglian’s Lincolnshire and Fens reservoirs anchor the East.
  3. 03Thames’s SESRO at Abingdon is the keystone — and the precedent.
  4. 04Havant Thicket is the first UK reservoir under construction since 1992.
  5. 05The Severn-Thames Transfer is the largest UK inter-regional transfer ever proposed.
  6. 06Water recycling (Teddington, Beckton) brings IPR to UK public supply.
  7. 07The SRO programme reopens UK reservoir construction at scale.
  8. 08RAPID coordinates the gated SRO approval process.
  9. 09PR24, PR29 and PR34 fund the WRMP24 25-year trajectory.
  10. 10Climate change and abstraction reform tighten the supply side.
  11. 11Industrial demand — data centre cooling — is the key WRMP29 uncertainty.
  12. 12Implications for undertakers, regulators, supply chain and Government.

Findings 01 – 09 follow in detail · pp. 10 – 12 · 10 – 12 summarised on the matrix

Quarterly Sector Report · Gap 372
112 · Findings 01 – 03
2 · Findings 01 — 03The portfolio · Anglian · SESRO
Finding 01 · MEDIUM

The SRO portfolio is the largest UK water build since the 1990s.

The Strategic Resource Options programme is the most significant UK water infrastructure construction programme since the 1990s — a £20–30 bn portfolio of reservoirs, inter-regional transfers, water recycling and desalination delivered across 2025–2040 to close the WRSE and WRE deficits and meet the 1-in-500 drought resilience standard by 2039. It is RAPID-coordinated and funded across PR24/PR29/PR34, with construction capex falling predominantly in PR29 (2030–2035) and commissioning in PR34. The portfolio at WRMP24 publication is the live RAPID set under active development; this report covers what is being built within it.

Finding 02 · HIGH

Anglian’s Lincolnshire and Fens reservoirs anchor the East.

Anglian Water leads two new public-supply reservoirs to address the long-standing East of England deficit: the Lincolnshire Reservoir (Sleaford area) and the Fens Reservoir (Chatteris area), both at RAPID Gate 2 (Development) at WRMP24 publication. Construction is expected in PR29 with commissioning in PR34, NSIP consent crossing the PR24/PR29 transition. Joint delivery programme management across the two schemes provides scale economies for Anglian Water and its supply chain — the largest UK reservoir construction programme since the 1990s, supporting the Cambridge-Peterborough growth corridor and inter-company transfer.

Finding 03 · HIGH

Thames’s SESRO at Abingdon is the keystone — and the precedent.

Thames Water’s South East Strategic Reservoir Option (SESRO), near Abingdon, is the most significant single SRO in the programme — substantial capacity for the Thames service area plus inter-company transfer to Affinity, Southern and South East Water. At RAPID Gate 2, its delivery is conditional on the Thames Water restructuring outcome (Gap 35, a substantial execution risk), the NSIP consent process, and cost progression through Gates 2–4. SESRO’s delivery and cost outcomes will set the precedent for the broader portfolio; if restructuring affects delivery, RAPID coordination, Special Administration Regime contingencies and portfolio adjustments may be required.

2 · 01 – 03Findings 04 – 06 · facing