Four hyperscalers signed 80% of the corporate PPA market. UK 2030 renewables now depend on it.
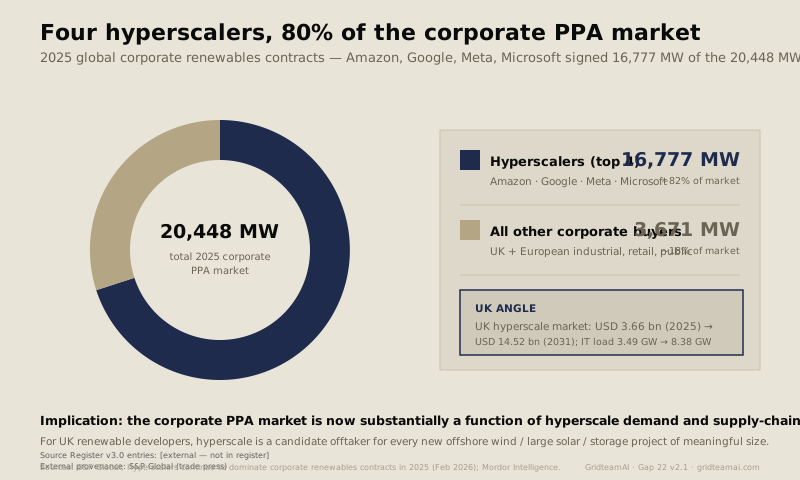
In 2025, Amazon (AWS), Google, Meta and Microsoft signed a combined 16,777 MW of corporate renewables contracts globally — approximately 80% of the 20,448 MW total corporate PPA market. The IT sector — overwhelmingly the hyperscale data centre segment — is the principal driver of new corporate renewable procurement.
Amazon has emerged as the largest corporate offshore wind offtaker globally, anchored by its offtake from East Anglia Three (Iberdrola, €5.2 billion / ~£4.4 billion equivalent), with six European offshore wind projects in portfolio. Google entered a 100 MW PPA with Moray West (Scotland), powering the Google Cloud UK region, with delivery from 2025.
The 24/7 Carbon-Free Energy methodology — hourly matching of consumption to carbon-free generation — is materially stricter than annual percentage-RE matching, and is reshaping the product. RE100 tightened its rules from January 2024 (assets <15 years old), reinforcing hyperscale appetite for new-build offshore wind, solar and long-duration storage.
GridteamAI · Quarterly Sector Report · Gap 22UK
06Executive summary · continued
Corporate PPAs and CfDs are complementary, not competitive.
AR7 (8,437.5 MW offshore wind at £91.20/MWh) and AR7a (6,232 MW at £65.23/MWh solar, £72.24/MWh onshore wind) CfD projects sit alongside corporate-PPA-funded projects; many split output across both. CfD provides regulatory price certainty, corporate PPA bilateral certainty — the combination reduces tail risk. Hyperscale PPA growth and CfD allocation growth are positively correlated, not negatively. The UK 2030 target depends on both routes.
European DC PPA volumes fell from 4.2 GW (2024) to 2.6 GW (2025) — a supply-pipeline pause, not a demand retreat. Volumes are expected to recover as new pipeline matures and Round 5 floating wind reaches offtake readiness.
The volume's argument
The UK 2030 renewable target is being part-funded by hyperscale corporate offtake on a scale that did not exist before 2022. This is positive for project bankability — but it creates concentration risk, and raises the question of who pays for residual non-hyperscale demand. Policy and market design must work for both routes simultaneously.
The shape of this volume. Section 1 sets out the headline figures. Section 2 develops twelve findings, each confidence-annotated. A chapter-weight pull at p. 14 anchors the argument. Section 3 sets out the buyer class and the named deals. Section 4 develops 24/7 CFE and the CfD interaction. Section 5 isolates concentration risk and emerging products. Section 6 makes recommendations, with a one-page tear-out at p. 25.
Executive summary · ends1 · The headline figures · p. 07
Figure 1 · Four hyperscalers, 80% of the marketS&P Global · 2025
16,777 of 20,448 MW signed by the top four in 2025.
Amazon, Google, Meta and Microsoft took ~80% of the corporate PPA market; all other corporate buyers combined took 3,671 MW. The UK hyperscale market runs USD 3.66bn (2025) to 14.52bn (2031).
Fig. 1 / Section 3
The hyperscale share (indigo) dwarfs all other buyers (neutral). Hyperscale is now a candidate offtaker for every meaningful UK project.
Quarterly Sector Report · Gap 222 · Twelve findings · p. 10
09 — 102 · Six findings · 01 – 04 · 2×2 grid
2 · Twelve findings on the PPA market10
2 · Twelve findings on the PPA marketQ1 2028
Twelve findings. Each carries a confidence level.
HIGH — verified against a generator, offtaker, regulator, government department or industry-standard data source. MEDIUM — named industry analytics source cross-referenced to a primary source. LOW — GridteamAI scenario projection or interpretation, marked as such.
Findings 01 – 12 · summary
01Hyperscalers have become the dominant buyer class in the corporate PPA market.
02Amazon’s East Anglia Three offtake is a structural template.
03Google’s Moray West PPA is the UK Cloud-region anchor.
04The 24/7 Carbon-Free Energy movement is reshaping the PPA product.
05RE100 tightened its rules and changed the UK eligibility map.
06European DC PPA volumes fell in 2025 despite demand growth.
07Corporate PPA pricing has firmed; long-tenor structures are dominant.
08Corporate PPAs and CfDs are structurally complementary, not competitive.
09Concentration risk is rising and raises policy questions.
10Storage PPAs and "firmed" renewable PPAs are emerging product lines.
11The UK PPA market interacts with Connections Reform and planning consent.
12Implications for developers, hyperscalers, generators, financiers and policy.
Findings 01–06 in detail · pp. 11–13 · 07–12 summarised above
Quarterly Sector Report · Gap 222
112 · Findings 01 – 02
2 · Findings 01 — 02The buyer class · the EA3 template
Finding 01 · HIGH
Hyperscalers have become the dominant buyer class in the corporate PPA market.
S&P Global’s annual review (February 2026) confirmed that Amazon, Google, Meta and Microsoft signed a combined 16,777 MW of corporate renewables contracts in 2025 — approximately 80% of the 20,448 MW market. This is not an emerging trend; it is the established structure of the market. The implication is that the corporate PPA market is now substantially a function of hyperscale demand and supply-chain constraints. Other corporate buyers continue to procure, but at volumes an order of magnitude below hyperscale. For UK renewable developers, "who is your offtaker?" increasingly has hyperscale as a candidate answer; for Government, corporate PPA volumes are a sensitive indicator of hyperscale capital allocation rather than a broad measure of corporate climate ambition.
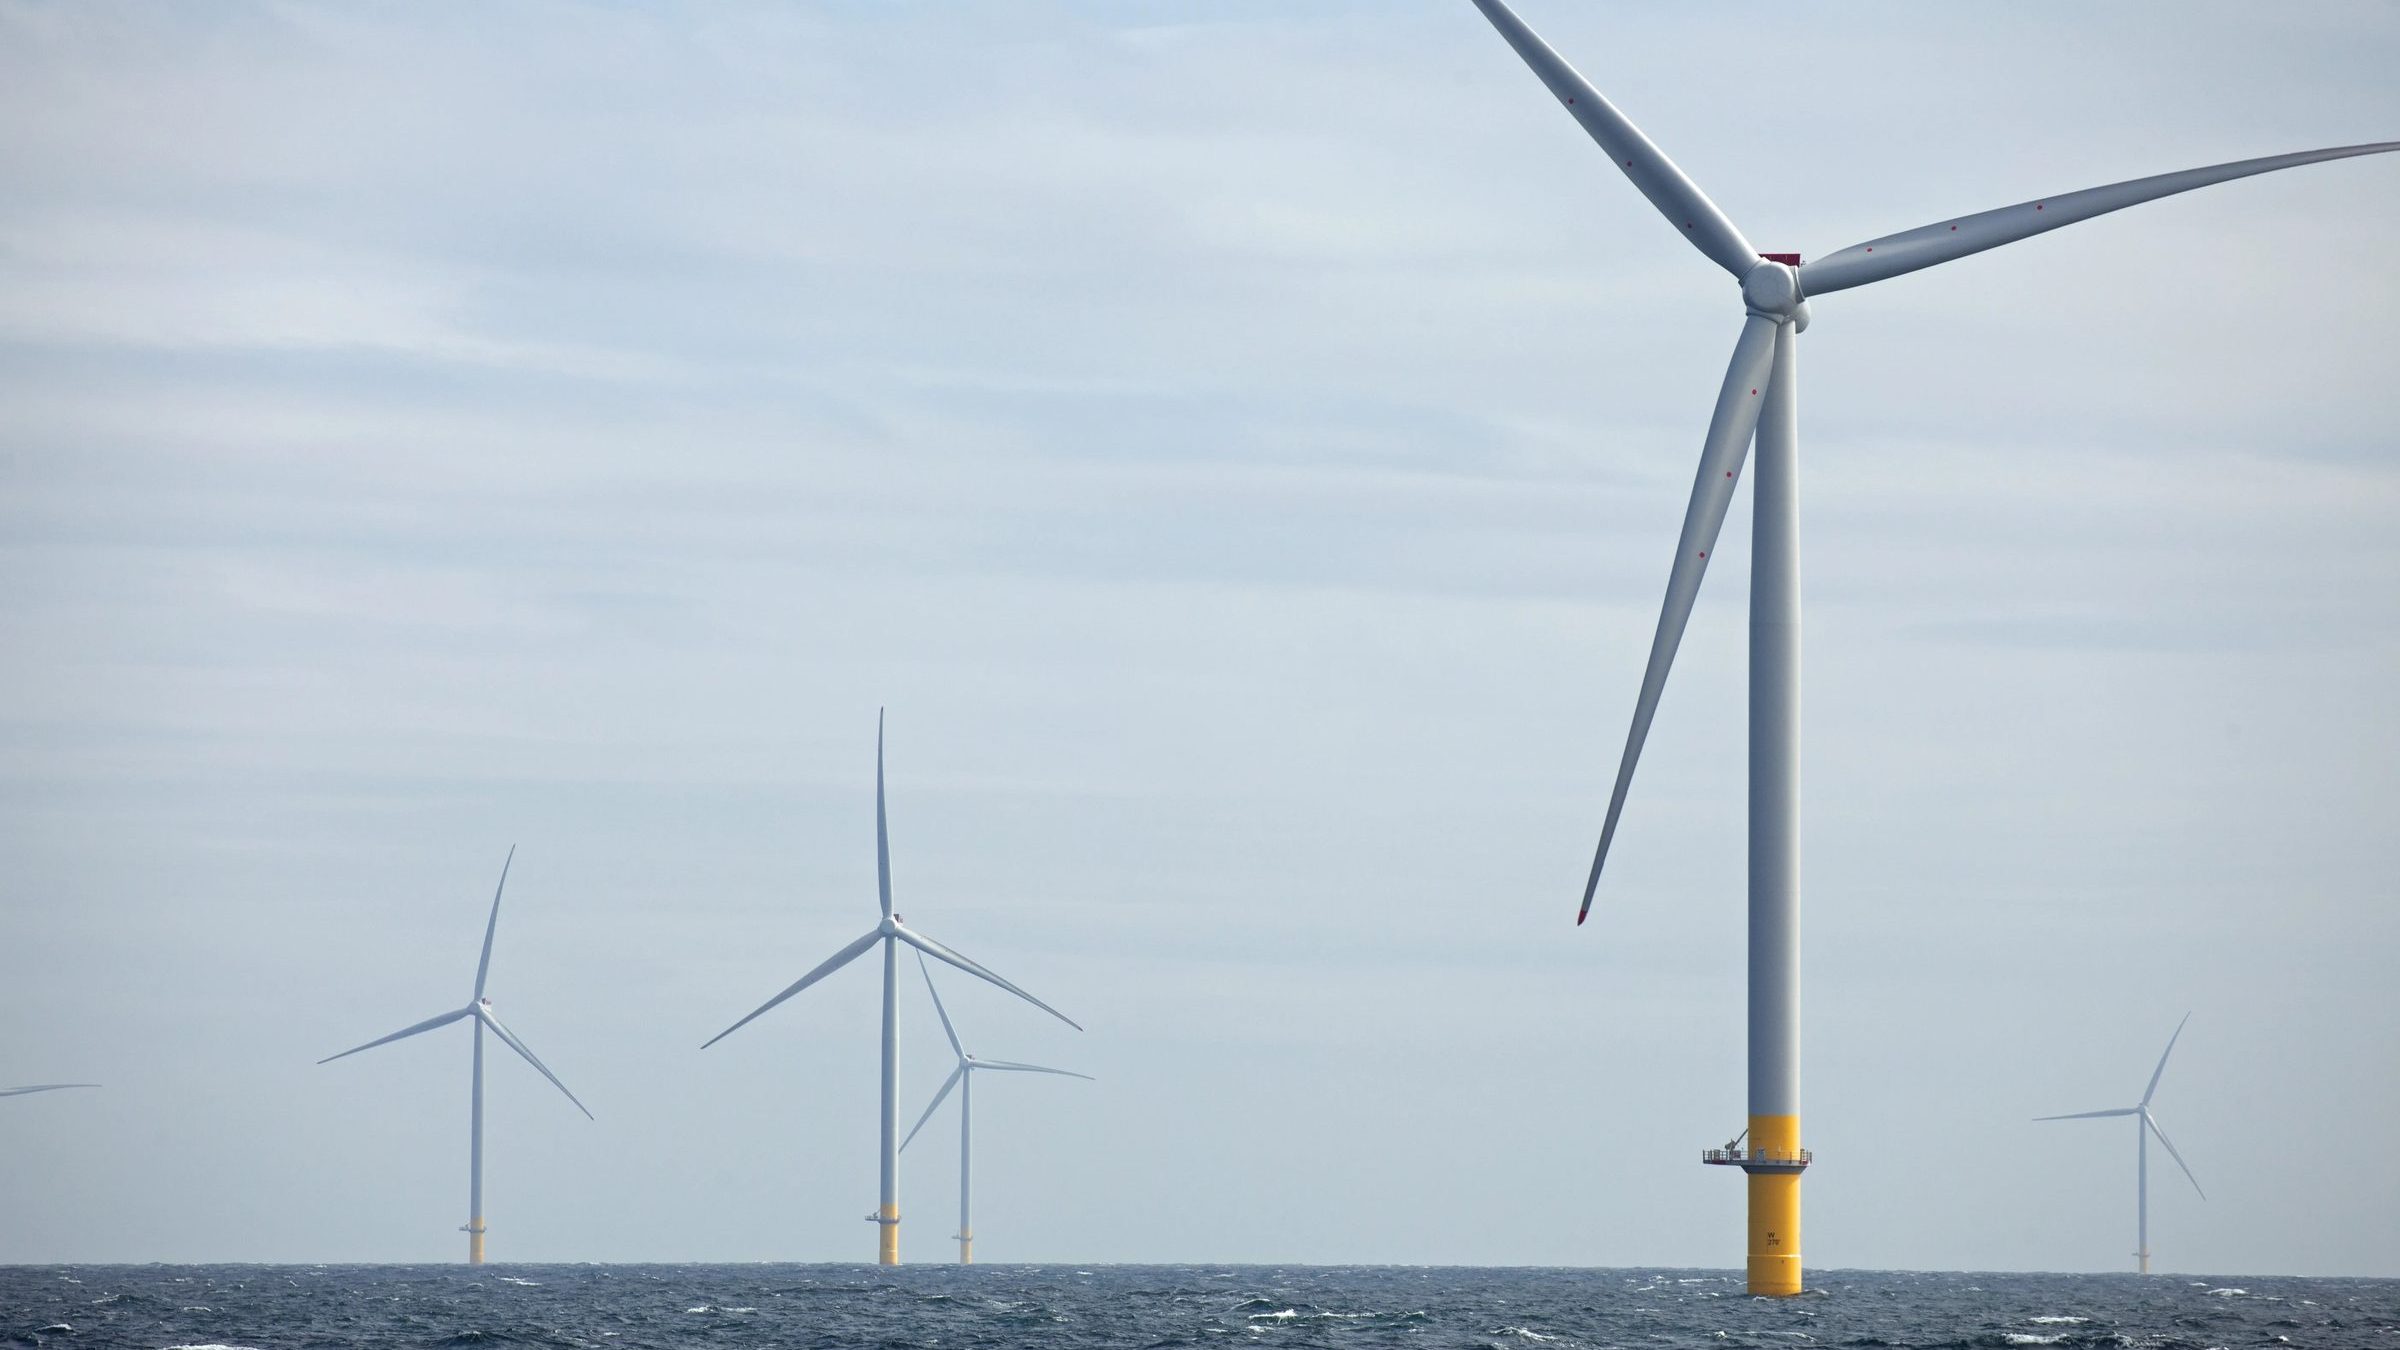
Hornsea One, North Sea — close-up turbine.Photo: Ørsted press centre
Sources · S&P Global (February 2026) · corporate renewables review
Finding 02 · HIGH
Amazon’s East Anglia Three offtake is a structural template.
Amazon’s offtake from East Anglia Three — the €5.2 billion (~£4.4 billion equivalent) Iberdrola / ScottishPower offshore wind project — is the most-cited reference deal for a UK-anchored hyperscale offshore wind PPA. It matters for three reasons: scale (substantial enough to underwrite a major component of a multi-gigawatt project, showing corporate PPAs can complement or replace CfD revenue at project-finance level); counterparty (Iberdrola / ScottishPower is one of Europe’s largest offshore wind developers); and tenor (long enough — typically 12–20 years — to underpin project-finance debt). The six-project Amazon European portfolio suggests a strategic decision to anchor European demand in offshore wind specifically — better load-factor match to baseload, RE100 new-build eligibility, and net-zero alignment.
Walney Extension, Irish Sea — sunset.Photo: Ørsted press centre
 GridteamAI