Five zones designated. £28.2 billion generated. A delivery package set out.
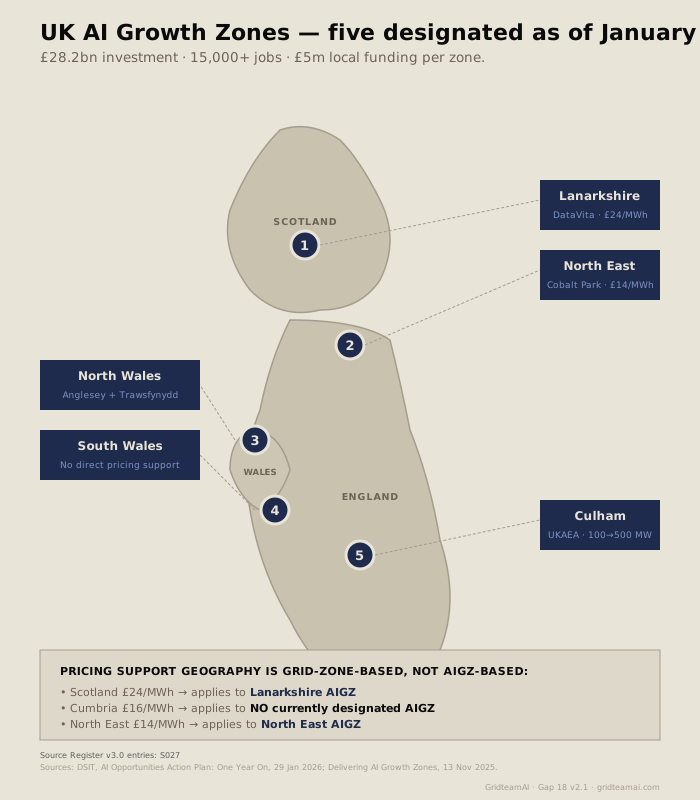
Five AI Growth Zones have been designated across Great Britain — 2 in Wales, 1 in Scotland, 2 in England: Culham (Oxfordshire pilot, at UKAEA), North East (Cobalt Park + Blyth), North Wales (Anglesey + Trawsfynydd), South Wales, and Lanarkshire (DataVita, near Glasgow).
The programme generated £28.2 billion of investment and more than 15,000 jobs in its first year, with £5 million of targeted funding for each zone. The Delivering AI Growth Zones paper (13 November 2025) sets out the grid, energy, planning, skills and investment package to carry zones from designation to delivery.
The package promises up to a 5-year reduction in time-to-power, up to £80m annual electricity savings for a 500 MW data centre, up to £100bn of unlocked investment and more than 10,000 jobs — alongside an energy-pricing support mechanism (£24/£16/£14 per MWh) from April 2027, and the AIGZ Delivery Unit launched January 2026.
GridteamAI · Quarterly Sector Report · Gap 18UK
06Executive summary · continued
The energy-pricing support is structurally novel — and locationally specific.
From April 2027 (subject to legislative timetables), data centres in eligible regions see electricity-cost discounts of up to £24/MWh in Scotland, £16/MWh in Cumbria and £14/MWh in the North East, with a 2030 review. The discount geography reflects grid-constrained zones driven by surplus wind — not AIGZ boundaries: Scotland maps to Lanarkshire, North East to the North East AIGZ; Cumbria has no designated AIGZ; Wales and Culham sit outside the discount regions.
The mechanism is funded by recycling grid constraint-cost savings — designed to add no cost for other electricity billpayers.
The volume's argument
The AIGZ programme has cleared the policy-design hurdle. The Q1 2027 picture will turn on operational delivery: whether the Connections Accelerator Service has cut connection times, whether the energy-pricing support commences in April 2027, whether the National Policy Statement for Data Centres is published with CNP status, and whether the first zones have moved from designation to groundbreaking.
The shape of this volume. Section 1 sets out the headline figures. Section 2 develops six findings, each confidence-annotated. A chapter-weight pull at p. 14 anchors the argument. Section 3 decodes the six-element AIGZ architecture. Section 4 steps through the five designated zones. Section 5 isolates the grid, energy-pricing and planning reforms. Section 6 makes recommendations, with a one-page tear-out at p. 25.
Executive summary · ends1 · The headline figures · p. 07
Figure 1 · The five designated AIGZsDSIT · Jan 2026
Five zones — 2 in Wales, 1 in Scotland, 2 in England.
The geography is deliberately UK-wide, each zone tied to anchoring infrastructure: UKAEA at Culham, Cobalt Park in the North East, SMRs in North Wales, DataVita’s micro-grid in Lanarkshire.
Fig. 1 / Section 1
Each zone is tied to a credible anchoring institution. The discount geography (bottom panel) is grid-zone-based, not AIGZ-based.
Quarterly Sector Report · Gap 182 · Six findings · p. 10
09 — 102 · Six findings · 01 – 04 · 2×2 grid
2 · Six findings on the AIGZ programme10
2 · Six findings on the AIGZ programmeQ1 2027
Six findings. Each carries a confidence level.
HIGH — anchored to a verified DSIT / gov.uk position. MEDIUM — DSIT direction of travel with material implementation questions still open. LOW — GridteamAI inference where the source supports direction but not magnitude or pacing.
Findings 01 – 06 · summary
01Five AI Growth Zones are now designated and operationally distinct.
02The programme generated £28.2bn of investment and 15,000+ jobs in year one.
03The energy-pricing support mechanism is structurally novel and locationally specific.
04The AIGZ Delivery Unit is the operational cross-government coordination mechanism.
05The grid-side intervention is comprehensive — reallocation, reservation and the CAS.
06Planning reforms include a National Policy Statement for Data Centres and CNP status.
Each finding follows in detail · pp. 11 – 13
Quarterly Sector Report · Gap 182
112 · Findings 01 – 02
2 · Findings 01 — 02Five zones · the £28.2bn trajectory
Finding 01 · HIGH
Five AI Growth Zones are now designated and operationally distinct.
The AI Opportunities Action Plan: One Year On (29 January 2026) verifies five AIGZs designated across Great Britain — 2 in Wales, 1 in Scotland, 2 in England. Each is tied to anchoring infrastructure: UKAEA at Culham (100→500 MW); Cobalt Park + Blyth in the North East; Anglesey + Trawsfynydd (near new SMRs) in North Wales; South Wales; and DataVita’s micro-grid in Lanarkshire. This is not a "designate the land and see" framework — it ties each zone to a credible anchoring institution.
Sources · DSIT One Year On (29 Jan 2026) · Computer Weekly · Data Center Dynamics · CMS Law
Finding 02 · HIGH
The programme generated £28.2bn of investment and 15,000+ jobs in year one.
The One Year On document records £28.2 billion of investment generated, more than 15,000 jobs created, and £5 million of targeted funding per zone in the programme’s first year. Against the Delivering AIGZ paper’s "up to £100 billion" ambition, year-one delivery has secured roughly 28% of the longer-term target — a verifiable scale of capital-attraction success. The Q1 2027 question is whether the pace sustains as the programme moves from announcement to operational delivery.
Sources · DSIT One Year On (29 Jan 2026) · Delivering AIGZ (13 Nov 2025)
 GridteamAI