← GridteamAI

Purchase access

This is part of the paid GridteamAI Quarterly Sector Report.

Purchase access — book@gridteamai.com

£295 single volume · £995/yr annual · Team £2,495 · Enterprise £4,995 · Corporate £9,995. Secure checkout coming soon; email to purchase today.

GridteamAI · Quarterly Sector Report · Gap 08
The AR7 Decode — record 14.7 GW awarded across 201 projects, £27 bn private investment
Series consistency · canonical Gap-series system
A4 · 210 × 297 mm · 3 mm bleed (not shown)
UK English · 2026 edition · v1.0
FRONT MATTERi · Cover · ink · full bleed
GridteamAI
Quarterly Sector Report
Volume Gap 08
Renewables Generation
by GridteamAI
UK · CfD Allocation Round 7 · AR7 + AR7a · Renewables United Kingdom · Q4 2027

The AR7
Decode.

Record 14.7 GW awarded across 201 projects, and the strike-price benchmark for UK clean power to 2030.

gridteamai.com · book@gridteamai.com 2026 edition · v1.0 Consultancy-grade deliverable
05 — 06Executive summary · spread
The AR7 Decode · Executive summary05
00 · Executive Summary A two-page brief

The framework delivered at scale. 14.7 GW awarded, every technology below its strike price.

The AR7 + AR7a allocation results (14 Jan / 10 Feb 2026) awarded a record 14.7 GW of clean-power capacity across 201 projects, mobilising an expected £27 bn of private investment. Every technology cleared below its Administrative Strike Price.

Offshore wind — the headline tranche at 8.4 GW — cleared at £91.20/MWh (2024 prices), a 19.29% saving against the £113 cap. Solar cleared a record 4.9 GW at £65.23; onshore 1.3 GW at £72.24; floating offshore wind reached a first material 192.5 MW at £216.49; tidal 20.9 MW at £265.00.

Delivery is England-heavy in solar and offshore, Scotland-dominated in onshore, and Welsh-led in floating and tidal. Twelve offshore-wind CfD units across eight named sites form the 2028–2031 backbone. AR7 + AR7a delivers ~6.5–7.4% of the Clean Power 2030 envelope from one round.

The Q3 2027 picture

By delivery, the AR7 + AR7a cohort commissions across 2027/28–2032/33; budget impact rises to £1,784m on offshore Pot 3 by 2032/33; the named twelve offshore units carry the bulk of the capacity; and AR8 design resets strike-price expectations to AR7 clearing levels.

The shape of this volume. Section 1 sets out the headline figures. Section 2 develops twelve findings, each confidence-annotated. A chapter-weight pull at p. 14 anchors the argument. Section 3 sets out the AR7 architecture — Pots, pay-as-clear and the 15-year strike price. Section 4 maps the named project portfolio. Section 5 covers budget impact and regional distribution. Section 6 makes recommendations, with a one-page tear-out at p. 25.

Executive summary · ends1 · The headline figures · p. 07
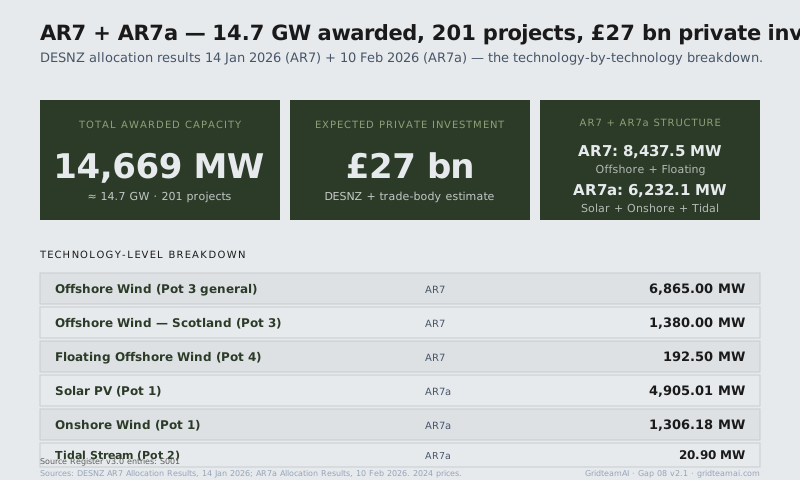
09 · FIG. 11 · AR7 + AR7a headline totals · restyled -v2
1 · The headline figures09
Figure 1 · AR7 + AR7a headline totalsDESNZ · Jan–Feb 2026

14.7 GW awarded across 201 projects — the technology-by-technology breakdown.

£27 bn expected private investment; AR7 8,437.5 MW (offshore + floating), AR7a 6,232.1 MW (solar + onshore + tidal).

AR7 + AR7a headline totals: 14,669 MW awarded across 201 projects, £27 bn expected private investment, AR7 8,437.5 MW and AR7a 6,232.1 MW, with the technology-level breakdown by capacity.
Fig. 1 / Section 1

The three moss headline panels carry the totals; the technology breakdown table sits below. Offshore wind is the headline tranche at 8.2 GW.

Quarterly Sector Report · Gap 082 · Twelve findings · p. 10
09 — 102 · Twelve findings · 01 – 03
2 · Twelve findings on AR7 + AR7a10
2 · Twelve findings on AR7 + AR7aQ4 2027

Twelve findings. Each carries a confidence level.

HIGH — verified against a NESO, Ofgem, DNO or DESNZ primary source. MEDIUM — named UK industry coverage cross-referenced to a primary source. None is forward-looking opinion unless framed as such.

Findings 01 – 12 · summary

  1. 01AR7 + AR7a is the largest single auction outcome in UK CfD history — 14.7 GW.
  2. 02AR7 cleared 8.4 GW of offshore wind at £91.20/MWh (2024 prices).
  3. 03AR7a cleared 4.9 GW of solar at £65.23/MWh — a record UK solar allocation.
  4. 04AR7a cleared 1.3 GW of onshore wind at £72.24/MWh — first major round post-NPPF reset.
  5. 05AR7 cleared the first material floating offshore wind allocation — 192.5 MW.
  6. 06AR7a cleared 20.9 MW of tidal stream at £265.00/MWh.
  7. 07Twelve offshore wind CfD units across eight wind-farm sites are the 2028–31 backbone.
  8. 08Every technology cleared below its Administrative Strike Price — ~20% average.
  9. 09Budget impact rises across delivery years, front-loaded by the large later projects.
  10. 10Geography: England-heavy in solar and offshore, Scotland in onshore, Wales in floating and tidal.
  11. 11AR7 + AR7a delivers ~6.5–7.4% of the Clean Power 2030 envelope from one round.
  12. 12The Q4 2027 picture: project delivery in flight, supply-chain pressure, AR8 in design.

Findings 01 – 09 follow in detail · pp. 10 – 14 · 10 – 12 summarised on the matrix

Quarterly Sector Report · Gap 082
112 · Findings 01 – 03
2 · Findings 01 — 03Record · offshore · solar
Finding 01 · HIGH

AR7 + AR7a is the largest single auction outcome in UK CfD history — 14.7 GW.

Dogger Bank South East and South West (RWE, 1,500 MW each, 2030/31); Norfolk Vanguard East and West (six CfD units, ~3,090 MW, 2028/29–2029/30); Berwick Bank Phase B (Scotland, 1,380 MW); Awel y Môr A (Wales, 775 MW); plus floating Erebus and Pentland. Twelve contract units across eight sites (six fixed-bottom + two floating) — the named backbone of UK offshore delivery, interacting with EGL transmission (Gap 11) and Welsh seabed leasing (Gap 16).

Finding 02 · HIGH

AR7 cleared 8.4 GW of offshore wind at £91.20/MWh.

Pot 3 offshore wind cleared at £91.20/MWh (2024 prices); Scotland-specific offshore at £89.49/MWh; Pot 3 total 8,245 MW, plus 192.5 MW floating (Pot 4) = 8,437.5 MW. The 19.29% saving against the £113/MWh Administrative Strike Price reflects a matured strike-price band around £89–91/MWh — global supply-chain pressure on cable, vessels and turbines (Gap 11) against the value of CfD revenue stabilisation.

Finding 03 · HIGH

AR7a cleared 4.9 GW of solar PV at £65.23/MWh — a record UK solar allocation.

4,905.01 MW across 157 successful projects (72 delivering 2027/28, 85 in 2028/29), a 13.03% saving against the £75/MWh Administrative Strike Price. Heavily England-concentrated: 4,247 MW (86.6%); Scotland and Wales ~330 MW each. West Burton (three sites, 480 MW) is the largest single cluster. Structurally significant for the wider UK solar pipeline (Gap 10).

2 · 01 – 03Findings 04 – 06 · facing