The mandate is built. The market is scaling. The kWh you do not consume is the kWh you do not build.
The Ofgem RIIO-ED3 SSMD (21 May 2026) made Build-and-Flex a mandatory first-stage obligation: DNOs must systematically assess flexibility before reinforcement, funded through distinct allowances, with the TIM-substitution channel closed.
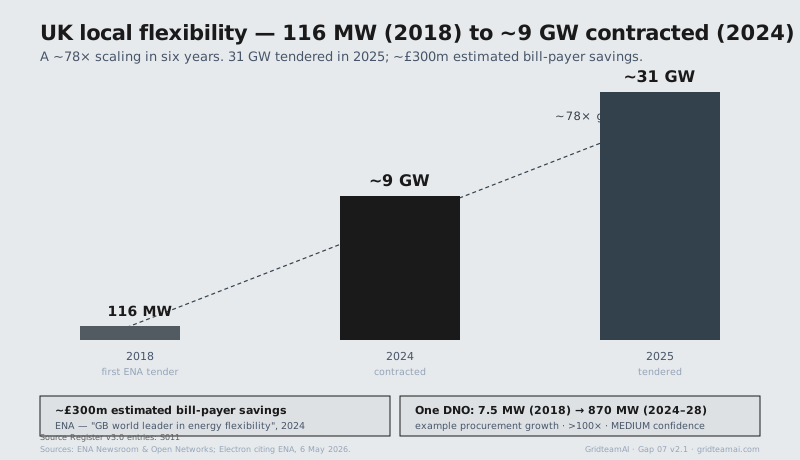
The market has scaled from 116 MW contracted in 2018 to roughly 9 GW in 2024 — an estimated £300m in bill-payer savings — with 31 GW tendered in 2025. The Clean Flexibility Roadmap sets 55.2 GW by 2030 and 204 GW by 2050.
Elexon became market facilitator in December 2025, coordinating 20+ markets. The DFS reached 2.46m participants and went bi-directional on 9 April 2026. MHHS settlement completes by May 2027.
GridteamAI · Quarterly Sector Report · Gap 07UK
06Executive summary · continued
Flexibility is no longer a sustainability commitment. It is a mandated procedural step — and a structural revenue line.
The four ENA Open Networks standardised products — Peak Reduction, Operational Utilisation, Scheduled Utilisation, and Operational Utilisation & Variable Availability — let aggregators build portfolios across DNO regions with comparable contracts. The Standardised DNO Settlement Methodology (v1.1, March 2025) provides the common framework.
The Q3 2027 picture
Contracted volumes projected at 15–20 GW on the 2030 trajectory; DNO procurement portfolios structured around the four products plus LV expansion; DFS participation well beyond 2.46m; MHHS in final completion; the Build-and-Flex obligation codified in the December 2026 final business plans, reviewed at Draft Determinations in summer 2027.
The shape of this volume. Section 1 sets out the headline figures. Section 2 develops twelve findings, each confidence-annotated. A chapter-weight pull at p. 15 anchors the argument. Section 3 sets out the market architecture and the four products. Section 4 maps DNO procurement and the Elexon facilitator role. Section 5 covers the DFS and the MHHS settlement architecture. Section 6 makes recommendations, with a one-page tear-out at p. 26.
Executive summary · ends1 · The headline figures · p. 07
Figure 1 · Local flexibility market growthENA · 2018–2025
116 MW in 2018 to ~9 GW contracted in 2024 — a ~78× scaling.
31 GW tendered in 2025; ~£300m in estimated bill-payer savings; one DNO grew procurement from 7.5 MW to 870 MW.
Fig. 1 / Section 1
The 2025 tendered bar (steel) shows the trajectory; the 2018 baseline (slate) is a market that barely existed. Tendered consistently outpaces contracted.
Quarterly Sector Report · Gap 072 · Twelve findings · p. 10
09 — 102 · Six findings · 01 – 04 · 2×2 grid
2 · Twelve findings on the UK flexibility market10
2 · Twelve findings on the UK flexibility marketQ2 2027
Twelve findings. Each carries a confidence level.
HIGH — verified against a NESO, Ofgem, DNO or DESNZ primary source. MEDIUM — named UK industry coverage cross-referenced to a primary source. None is forward-looking opinion unless framed as such.
Findings 01 – 12 · summary
01Build-and-Flex is now a mandatory first-stage obligation under the SSMD.
02Flexibility scaled from 116 MW (2018) to ~9 GW contracted (2024).
Findings 01 – 09 follow in detail · pp. 10 – 14 · 10 – 12 summarised on the matrix
Quarterly Sector Report · Gap 072
112 · Findings 01 – 03
2 · Findings 01 — 03The mandate · the scaling · the roadmap
Finding 01 · HIGH
Build-and-Flex is now a mandatory first-stage obligation under the RIIO-ED3 SSMD.
The Ofgem SSMD (21 May 2026) elevated Build-and-Flex from an optional optimisation choice to a mandatory first-stage obligation. Flexibility is funded through distinct allowances, separate from network-building; the TIM-substitution channel is closed. A DNO that has not systematically assessed flexibility before committing to reinforcement is non-compliant with the SSMD-mandated process. (Full treatment in Gap 05 Finding 01.)
Finding 02 · HIGH
UK flexibility scaled from 116 MW (2018) to ~9 GW contracted (2024).
Per ENA's “GB cements status as world leader in energy flexibility” reporting, 9 GW was contracted in 2024 with estimated bill-payer savings of ~£300 million — a >75× scaling from the 116 MW first Open Networks tender in 2018. The market has moved past the pilot phase into a Tier-1 segment of UK power-sector operations. 31 GW was tendered in 2025.
Finding 03 · HIGH
The Clean Flexibility Roadmap sets 55.2 GW (2030) and 204 GW (2050) targets.
NESO + Ofgem published the Roadmap in July 2025: total flexibility capacity of 55.2 GW by 2030 and 204 GW by 2050 — roughly a 6× growth from the 9 GW 2024 baseline. NESO has parallel targets of 12 GW consumer-led flexibility by 2030 and a minimum 750 MW of industrial and commercial flexibility through its own markets.
 GridteamAI