The fleet is real. The queue is closed. The next question is the 55 GW threshold.
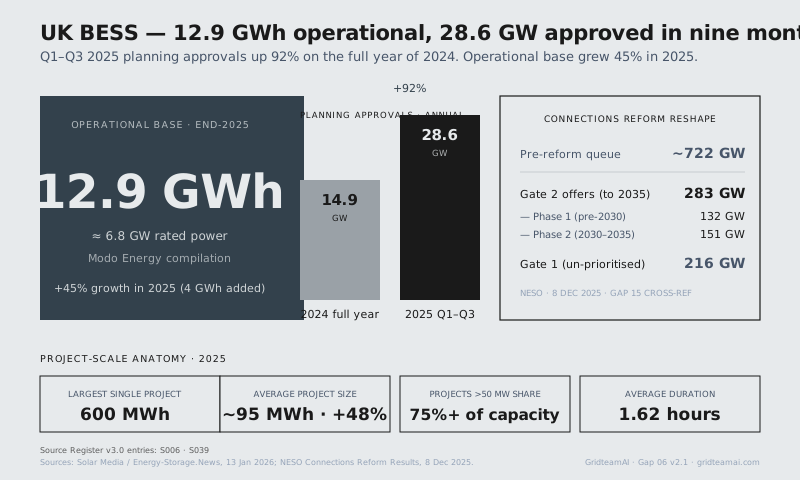
The operational fleet reached 12.9 GWh at end-2025 — a 45% year-on-year rise, with 4 GWh added in the year. Planning approvals scaled to 28.6 GW in the first three quarters of 2025 alone, up 92% on all of 2024.
NESO's Connections Reform Results (8 December 2025) issued 83 GW of Gate 2 offers to BESS — 33 GW pre-2030, 50 GW for 2030–2035 — but cut 153 GW from the queue and identified a 62 GW oversupply by 2035. Only “protected” projects received offers.
For all practical purposes, new short-duration BESS cannot connect before 2035 unless 55 GW leaves the pipeline or the Strategic Spatial Energy Plan raises the allowance. Long-duration storage runs on its own cap-and-floor track toward Summer 2026 final awards.
GridteamAI · Quarterly Sector Report · Gap 06UK
06Executive summary · continued
The question has moved from “how many MW are in the pipeline?” to “how much commissioned capacity is operating?”
The market is consolidating. Average project size grew 48% in 2025 to ~95 MWh; the UK's largest single BESS reached 600 MWh; over 75% of 2025 capacity came from projects above 50 MW; 61% of operational projects are standalone. Average duration is 1.62 hours and rising as longer-duration projects commission.
The Q2 2027 picture
Operational fleet projected at 18–22 GWh; the 33 GW Phase 1 protected cohort in active build-out; LDES Window 1 awardees at or near FID; aggregator-mediated portfolio participation the dominant revenue model. The 55 GW threshold has most likely not yet been met.
The shape of this volume. Section 1 sets out the headline figures. Section 2 develops twelve findings, each confidence-annotated. A chapter-weight pull at p. 15 anchors the argument. Section 3 sets out the Connections Reform impact. Section 4 maps the operational fleet and 2025 market anatomy. Section 5 isolates the LDES cap-and-floor framework. Section 6 makes recommendations, with a one-page tear-out at p. 26.
Executive summary · ends1 · The headline figures · p. 07
Figure 1 · The operational fleet and the pipelineSolar Media · NESO · 2025–26
12.9 GWh operational, 28.6 GW approved in nine months — against a restructured queue.
The operational base grew 45% in 2025; planning approvals ran 92% ahead of 2024; Connections Reform reshaped a ~722 GW queue into 283 GW of Gate 2 offers.
Fig. 1 / Section 3
The operational base (steel) anchors the picture; the approvals jump and the queue reshape sit alongside. Approvals lead commissioning by 18–36 months.
Quarterly Sector Report · Gap 062 · Twelve findings · p. 10
09 — 102 · Six findings · 01 – 04 · 2×2 grid
2 · Twelve findings on the UK BESS pipeline10
2 · Twelve findings on the UK BESS pipelineQ2 2027
Twelve findings. Each carries a confidence level.
HIGH — verified against a NESO, Ofgem, DNO or DESNZ primary source. MEDIUM — named UK industry coverage cross-referenced to a primary source. None is forward-looking opinion unless framed as such.
Findings 01 – 12 · summary
01The operational fleet reached 12.9 GWh at end-2025.
02Planning approvals scaled to 28.6 GW in Q1–Q3 2025 alone.
Findings 01 – 09 follow in detail · pp. 10 – 14 · 10 – 12 summarised on the matrix
Quarterly Sector Report · Gap 032
112 · Findings 01 – 03
2 · Findings 01 — 03The fleet · the approvals · the reform
Finding 01 · HIGH
The operational fleet reached 12.9 GWh at end-2025, with 4 GWh added in the year.
Per Solar Media Market Research / Energy-Storage.News (13 January 2026), the UK grid-scale battery market grew 45% by operational capacity in 2025. The significance is twofold: 12.9 GWh is a foundational scale, sufficient to support meaningful flexibility-services participation across wholesale, balancing and ancillary markets; and the growth rate, down from 53% in 2024, reflects a maturing market — larger projects, more capital discipline, early effects of merchant-revenue concern. Projected Q2 2027 fleet: 18–22 GWh.
Finding 02 · HIGH
Planning approvals scaled to 28.6 GW in the first three quarters of 2025 alone.
Per ESS-News (7 January 2026), planning permission was granted to 28.6 GW of BESS in Q1–Q3 2025, up 92% on the 14.9 GW approved in all of 2024. Maturing legal precedent, RIIO-ED3 build-and-flex appetite, and the Clean Power 2030 disposition have together unblocked the planning side. But Connections Reform means many consented projects without protected status become a queue of “consent-ready-but-connection-blocked” assets pending the 55 GW threshold.
Finding 03 · HIGH
Connections Reform issued 83 GW of Gate 2 offers and cut 153 GW.
NESO's 8 December 2025 results delivered the reformed pipeline. For BESS: 83 GW received Gate 2 offers (33 GW Phase 1 pre-2030; 50 GW Phase 2 post-2030); 153 GW were not prioritised — Gate 1 or removed. Access has been deliberately narrowed to “protected” projects that had already significantly progressed and retained their connection dates. NESO's rationale: the queue contained an unsustainable volume of speculative BESS against a much smaller underlying need.
 GridteamAI