The queue was the problem. Connections Reform is the answer the country is now testing.
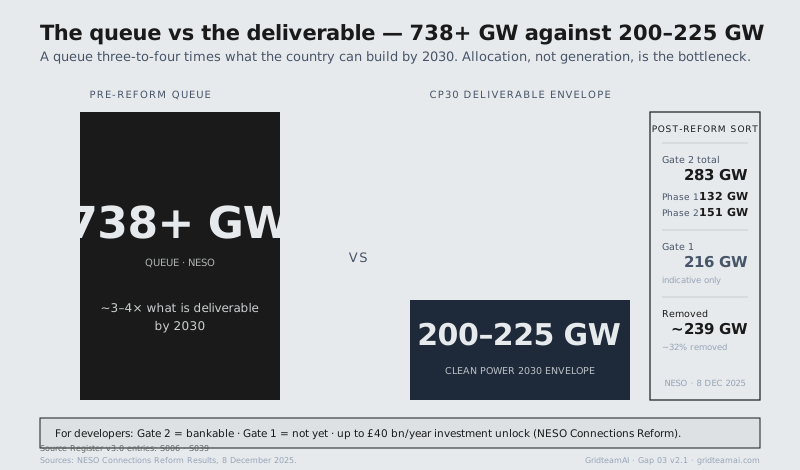
The pre-reform UK connections queue stood at over 738 GW — roughly three to four times the 200–225 GW the country can physically build by 2030. Allocation, not generation, was the bottleneck.
NESO's Connections Reform Results (8 December 2025) reshaped that queue into 283 GW of Gate 2 offers — the live pipeline, split 132 GW pre-2030 and 151 GW for 2030–2035 — plus 216 GW of Gate 1 indicative offers with a route but no contracted date.
The post-reform UK landscape is five GB DNO ownership groups across fourteen licence areas, writing RIIO-ED3 business plans due December 2026 against a 4.35% allowed return. The reformed regime moves from theory to practice between July 2026 and March 2027.
GridteamAI · Quarterly Sector Report · Gap 03UK
06Executive summary · continued
By the end of 2026 the question is not "can we connect?" but "which DNO, which Gate, which team moves fastest?"
Connections Reform converted a first-come-first-served queue into a CP30-aligned pipeline. About 140 data-centre facilities sit in the queue, aggregating to ~50 GW; roughly 13 GW is firm pre-2030, ~86 GW queued for 2030–2035. The post-reform pipeline is geographically concentrated — UK Power Networks, the M4 corridor, and Manchester / Slough / Cambridge hold the majority of strategic-demand pressure.
The window
Distribution Gate 2 offers open early July 2026 (Phase 1) and run to mid-March 2027 (Phase 2). DNO business plans are due December 2026; the ED3 control period runs 1 April 2028 → 31 March 2033. Q3 2026 is the last meaningful window to influence regional priorities.
The shape of this volume. Section 1 sets out the headline figures. Section 2 develops twelve findings, each confidence-annotated. A chapter-weight pull at p. 14 anchors the argument. Section 3 sets out the reformed pipeline. Section 4 maps the five GB DNO groups. Section 5 isolates the RIIO-ED3 window. Section 6 sets out stakeholder implications, with a one-page tear-out at p. 26.
Executive summary · ends1 · The headline figures · p. 07
Figure 1 · The queue against the deliverableNESO · 8 Dec 2025
738+ GW queued against a 200–225 GW deliverable envelope.
Connections Reform sorts the queue: 283 GW into Gate 2 (132 pre-2030 + 151 for 2030–2035), 216 GW into Gate 1, ~239 GW removed.
Fig. 1 / Section 1
The CP30 deliverable envelope (ochre) is roughly a quarter of the pre-reform queue. Allocation, not generation, is the bottleneck.
Quarterly Sector Report · Gap 032 · Twelve findings · p. 10
09 — 102 · Six findings · 01 – 04 · 2×2 grid
2 · Twelve findings10
2 · Twelve findings on UK DNO capacity headroomQ3 2026
Twelve findings. Each carries a confidence level.
HIGH — verified against a NESO, Ofgem, DNO or DESNZ primary source. MEDIUM — named UK industry coverage cross-referenced to a primary source. None is forward-looking opinion unless framed as such.
Findings 01 – 12 · summary
01The queue was three to four times the deliverable.
02Connections Reform has reshaped the queue around CP30 need.
03Iberdrola has consolidated the DNO map to five ownership groups.
04Build-and-flex becomes the default under RIIO-ED3.
05The DNO business-plan window closes in December 2026.
06Data centres are concentrated, not national.
07Regional Energy Strategic Plans arrive from 2026.
08The Gate 2 distribution offer window opens in early July 2026.
09Catch-up efficiency challenge retained as starting point.
10Sub-regional headroom narratives diverge by DNO.
11Q3 2026 forward outlook depends on Gate 2 throughput.
12Implications for developers, supply chain and SMEs.
Findings 01 – 09 follow in detail · pp. 11 – 13 · 10 – 12 summarised on the matrix
Quarterly Sector Report · Gap 032
112 · Findings 01 – 03
2 · Findings 01 — 03The queue · the reform · the consolidation
Finding 01 · HIGH
The queue was three to four times the deliverable.
The aggregate UK connections queue stood at over 738 GW pre-reform; the deliverable Clean Power 2030 envelope is approximately 200–225 GW. Even after Connections Reform sorts 283 GW into Gate 2 and 216 GW into Gate 1, more than 60% of queued projects will not hold a contracted connection date in the current decade. For any developer not yet inside the reformed pipeline the question is not when their connection comes — it is whether the project as currently scoped is still viable.
Finding 02 · HIGH
Connections Reform has reshaped the queue around CP30 need.
The 8 December 2025 NESO Connections Reform Results converted a first-come-first-served queue into a CP30-aligned pipeline. 132 GW of Gate 2 Phase 1 offers sit pre-2030, broadly matching the CP30 envelope of 200–225 GW. 151 GW of Gate 2 Phase 2 offers form the 2030–2035 build pipeline. 216 GW receives Gate 1 indicative offers — a route but no contracted date. The reform was negotiated with 60+ industry workgroups, 1,500 applications reviewed in five months, and 172 consultation responses.
Finding 03 · HIGH
Iberdrola has consolidated the DNO map to five ownership groups.
With Iberdrola's August 2025 completion of an 88% stake in Electricity North West — rebranded SP Electricity North West — the historic six-group GB DNO map has consolidated to five. SP Energy Networks now operates three licence areas under one parent. Bidder maps written before August 2025 are out of date: commercial conversations in two of the historic six regions are now coordinated from one corporate centre.
 GridteamAI